Why Non-Listed BDC Fundraising Is Slowing in 2026
Featured In: PEI
David Goldstein, Director of Fund Services at STP Investment Services, was featured in a recent PEI article examining the significant slowdown in non-listed business development company (BDC) fundraising during the first half of 2026. The article explores how liquidity concerns, longer fund life cycles, redemption activity, and investor sentiment are influencing the private credit landscape.
The Bigger Picture
Fundraising for non-listed BDCs experienced a significant decline during the first half of 2026. According to data cited in PEI, fundraising totaled $7.1 billion, down 70% from the $23.5 billion raised during the same period in 2025. At the same time, redemption requests reached record levels, highlighting growing investor demand for liquidity.
The decline comes after several years of rapid growth in private credit and retail alternatives, driven by strong investor demand for yield and diversification. However, changing market conditions, slower distributions, and concerns around investment time horizons are prompting some investors to reassess their allocations.
While retail investor sentiment appears to be shifting, institutional investors continue to show confidence in private credit as an asset class. This divergence may shape fundraising trends and capital flows across the alternatives landscape in the months and years ahead.
Key Takeaways
- Non-listed BDC fundraising declined significantly during the first half of 2026.
- Redemption requests reached record levels, indicating growing investor demand for liquidity.
- Investors are increasingly focused on investment duration and capital return timelines.
- Retail investors appear more cautious about private credit than institutional investors.
- Fund managers may face greater scrutiny around liquidity management, portfolio performance, and investor communications.
David Goldstein’s Perspective
As highlighted in the article, investors are paying closer attention to how long capital may remain invested before meaningful distributions occur.
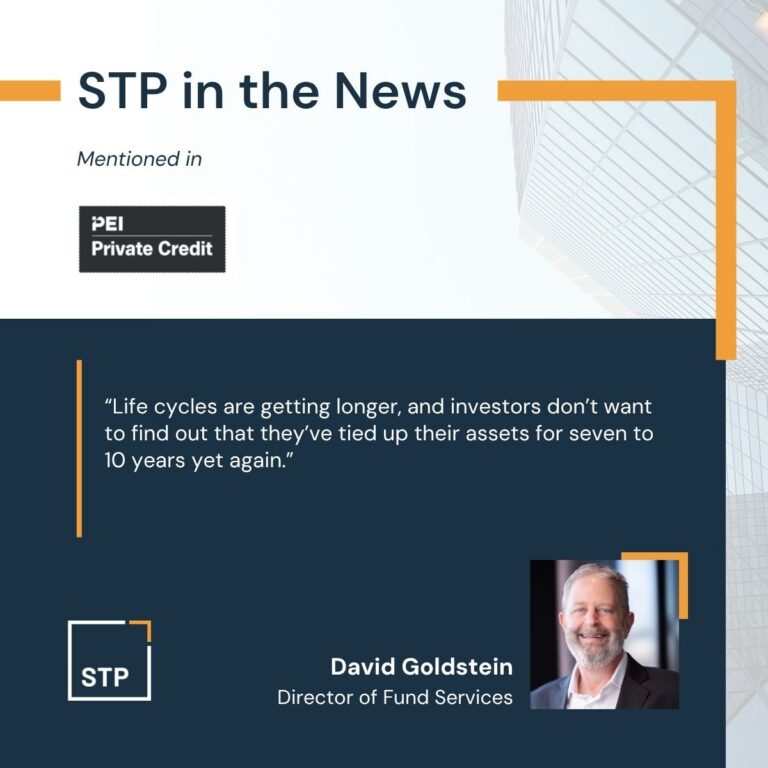
“Life cycles are getting longer, and investors don’t want to find out that they’ve tied up their assets for seven to 10 years yet again.”
— David Goldstein, Director of Fund Services, STP Investment Services
Goldstein also noted that while retail investors appear increasingly cautious about private credit, institutional investors largely remain constructive on the asset class, reflecting different investment objectives and liquidity expectations.
What This Means for Private Credit Managers
The slowdown in fundraising does not necessarily indicate a loss of confidence in private credit as an investment strategy. Instead, it reflects growing investor scrutiny around liquidity, capital deployment, and investment duration.
Today’s investors expect greater transparency around portfolio valuations, redemption policies, and expected timeframes for realizing returns. At the same time, managers are navigating market conditions that have made exits and distributions more challenging.
For private credit managers, this means investor communication is becoming increasingly important. Firms that clearly articulate portfolio strategy, liquidity management practices, and long-term value creation plans may be better positioned to maintain investor confidence during periods of market uncertainty.
As competition for investor capital increases, operational excellence, reporting transparency, and strong investor service capabilities may become even more important differentiators.
Action Steps for Fund Managers
- Review investor communication practices regarding liquidity expectations and fund timelines.
- Evaluate redemption management processes and liquidity planning frameworks.
- Enhance transparency around portfolio performance and valuation methodologies.
- Strengthen operational infrastructure to support increased investor inquiries and reporting needs.
- Monitor changing investor preferences across retail and institutional channels.
Frequently Asked Questions
What is a non-listed BDC?
A non-listed business development company (BDC) is an investment vehicle that provides financing to private businesses and is not traded on a public exchange.
Why is non-listed BDC fundraising declining?
According to data cited in the article, investors are becoming more cautious due to slower performance, liquidity concerns, and longer investment horizons.
Why are redemption requests increasing?
Many investors are seeking greater liquidity and access to capital as fund life cycles extend and market conditions remain uncertain.
Is private credit losing investor support?
The article notes that retail investors appear more cautious, while institutional investors remain generally positive about private credit as an asset class.
What should private credit managers focus on?
Managers should prioritize investor communication, transparency, liquidity management, and operational readiness to support evolving investor expectations.
Why It Matters
The decline in non-listed BDC fundraising highlights a broader conversation taking place across private markets: investors increasingly want both attractive returns and greater confidence around liquidity and investment timelines. As fundraising conditions evolve, managers that prioritize transparency, strong investor relationships, and operational excellence may be better positioned to maintain trust and attract capital. While private credit remains an important component of many portfolios, investor expectations around liquidity and flexibility continue to shape the future of the asset class.